Nexo
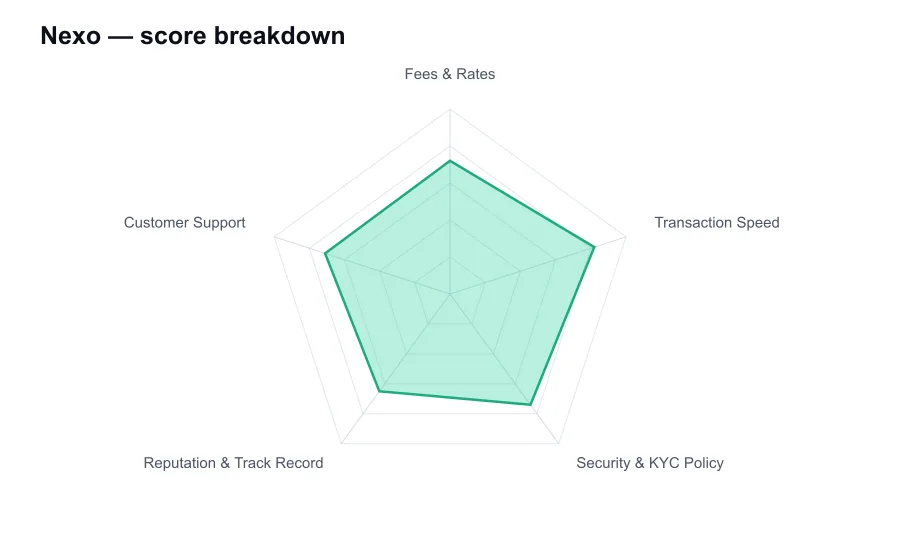
Nexo scores 7.3/10 overall in our independent review, measured against every other provider we've compared, strongest on Transaction Speed (8.2/10) and weakest on Reputation & Track Record (6.5/10).
7.3/10 ★★★★★ How we score → Visit official siteEditorial independence: our scores and rankings are produced using the fixed criteria above and are not influenced by advertisers. This is an independent ranking site and is not operated by, or affiliated with, any provider we list.
Affiliate disclosure: some links on this page may earn us a commission at no extra cost to you. This does not affect our rankings.
| Best for | Not for |
|---|---|
| Broad lending and yield toolkit | Earn products carry counterparty risk |
| Fast internal swaps | Regulatory restrictions vary by country |
Criteria & Scores
| Criterion | Score | Note |
|---|---|---|
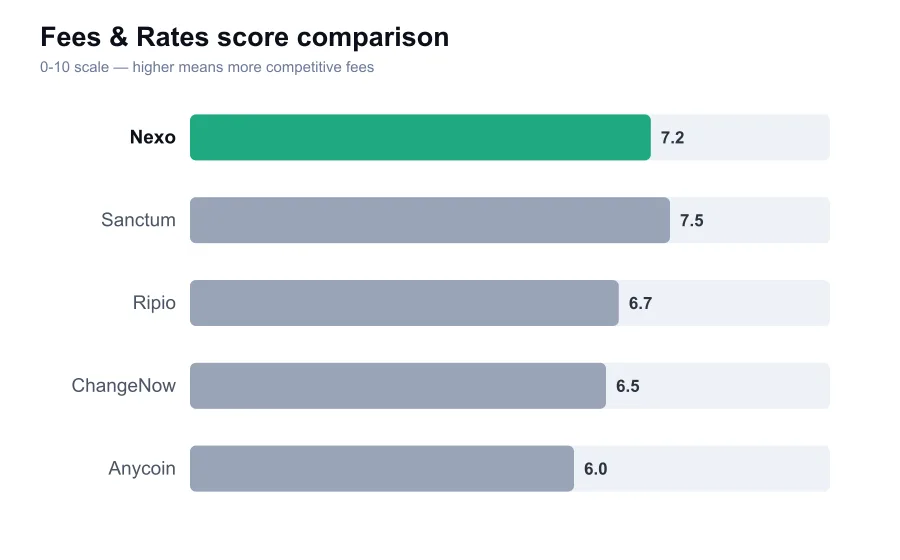
| Fees & Rates | 7.2 | Nexo Pro is competitive, retail swaps and loan terms need close reading. |
| Transaction Speed | 8.2 | Internal swaps are near-instant and withdrawals are often efficient. |
| Security & KYC Policy | 7.4 | Strong account controls, but custody and lending counterparty risk remain. |
| Reputation & Track Record | 6.5 | Survived major lender failures, with significant regulatory baggage. |
| Customer Support | 7.1 | Live chat helps, compliance cases can still be frustrating. |
In-Depth Review
Nexo occupies an unusual position in crypto. It is part lender, part yield platform, part exchange and part card issuer, built for people who want their coins to keep working without selling them. The promise is appealing: deposit crypto, earn interest, borrow against it, swap assets, and spend through a card. The trouble is that each of those activities adds a different layer of counterparty, market and regulatory risk.
Founded in 2018, Nexo grew quickly during the era when crypto credit looked like the industry's obvious next step. It survived the failures of Celsius, BlockFi and several other centralized lenders, which is a genuine point in its favor. Survival, however, isn't a free pass. The collapse of its peers changed the standard by which every crypto lender should be judged. Marketing claims and a polished app are no substitute for careful risk assessment.
Nexo's central product is the credit line. Users can pledge supported crypto assets as collateral and borrow stablecoins, fiat-linked funds or other assets without immediately creating a taxable sale in some jurisdictions. Loan-to-value ratios vary by collateral, and the interest rate depends heavily on the user's loyalty tier and NEXO token holdings. That structure is straightforward in calm markets. It becomes far less comfortable when collateral falls sharply and automatic liquidation is possible.
The platform advertises borrowing rates that can be very low for qualifying users, including promotional rates from 2.9 percent in certain high-collateral and loyalty conditions. Those are not the rates every customer receives. A user with a lower loyalty tier, a high loan-to-value ratio or volatile collateral can pay much more. Prospective borrowers should model a 30 to 50 percent drop in the collateral asset before treating a crypto-backed loan as cheap money.
Nexo's Earn product is similarly more complicated than the headline rate suggests. Rates differ by asset, lock-up term, loyalty tier, payout currency and jurisdiction. Extra yield for accepting rewards in NEXO tokens may look attractive, but it adds exposure to the platform's own token at precisely the point a customer may be trying to earn a conservative return. A stablecoin yield product is not a savings account, regardless of how calm the interface makes it feel.
For simple swaps, Nexo is fast. A conversion inside the app generally completes in seconds because it is an internal ledger operation rather than an on-chain trade. That is convenient for moving between Bitcoin, ETH and stablecoins, or for adjusting collateral quickly. It is not necessarily cheap. The easy swap interface includes a spread, and users looking for precise execution should use Nexo Pro or a dedicated spot exchange instead.
Nexo Pro is the better choice for anyone who actually wants to trade. Its fee schedule has used maker-taker pricing that can start near 0.07 percent maker and 0.20 percent taker at entry level, with lower rates at higher volume tiers. Those figures are materially more competitive than the retail swap spread, though they still need comparison with Binance, Kraken or Coinbase Advanced. Liquidity and available pairs remain more limited than at the largest exchanges.
Deposits are usually efficient, and Nexo has historically offered a number of free crypto withdrawals based on membership tier. That can be a real benefit, particularly for users moving assets occasionally. The terms matter. Free withdrawals are limited, network choice affects availability, and fiat transfer timing depends on banking rails and currency. Crypto withdrawals can take from minutes to longer if compliance or wallet-security checks are triggered.
Security is one of Nexo's stronger areas relative to smaller yield platforms. The company uses mandatory identity verification, two-factor authentication, withdrawal address controls and custodial security partners. It has also publicized third-party attestations and insurance arrangements for custodial assets. These measures are useful, but they should be read accurately. An attestation is not the same thing as a full public audit, and insurance does not mean every customer loss or market failure is covered.
Nexo's KYC stance is strict. Customers should expect identity verification before using the platform's core functions, and potentially source-of-funds checks for larger or unusual activity. Privacy-focused users will dislike that. I do not count it as a defect for a lending platform handling fiat rails, but the review process can be disruptive if a customer arrives expecting the frictionless anonymity associated with a self-custody wallet.
The reputational picture needs more than a slogan. Nexo paid a $45 million settlement in 2023 with the US Securities and Exchange Commission and state regulators over the unregistered offer and sale of its Earn Interest Product, without admitting or denying the findings. It had already stopped onboarding new US customers to Earn. Nexo also faced a high-profile investigation in Bulgaria, later reported as terminated after authorities found no evidence of criminal activity. These events do not prove the platform is unsafe, but they show the regulatory exposure is real.
Nexo's decision to leave or restrict certain markets has also affected users over time. Crypto regulation is fragmented, and yield products attract intense scrutiny. A customer should check their current country eligibility before depositing, not rely on a review written months earlier or on an old social-media post. Access to features can change based on where a person lives, even when the app itself remains available.
Customer support is better organized than the thin email-only model found at many crypto lenders. Nexo offers help-center resources and live chat, and routine matters can be handled quickly. The negative reports tend to cluster around exactly the cases that matter most: compliance reviews, withdrawal holds and account restrictions. That is common across centralized platforms, but it means users shouldn't keep funds on Nexo that they may need at a specific hour for an emergency.
The NEXO token deserves separate skepticism. It can improve rates, borrowing terms and withdrawal allowances, but it also creates a loyalty trap. Customers may buy the token to unlock benefits, then discover that the value of those benefits falls if the token price declines. Holding a platform token can make sense for a deliberate, closely monitored user. It is a poor substitute for evaluating whether the base product is attractive without incentives.
Nexo works best for experienced crypto holders who understand collateral ratios, accept full KYC and want a consolidated borrowing or yield tool. It is not the first platform I would recommend to a newcomer whose main goal is simply buying Bitcoin. Nor is it suitable for anyone who cannot tolerate temporary loss of access, price-driven liquidation or regulatory changes to product availability.
My final view is cautiously positive on Nexo's operational survival and product depth, but distinctly cautious about the lending model itself. It is more credible than many centralized yield platforms that collapsed, and Nexo Pro offers respectable trading costs. Yet the attractive headline rates are conditional, the token incentives complicate decisions, and regulation remains a live risk. Treat Nexo as a managed financial counterparty, not as a wallet or a bank.
Pros & Cons
| Pros | Cons |
|---|
Verdict
Frequently Asked Questions
Is Nexo safe for long-term crypto storage?
Nexo has meaningful security controls, but it remains a custodial lender and counterparty. Long-term holders who want maximum control should consider self-custody rather than leaving all assets on any lending platform.
What are Nexo's trading fees?
Nexo Pro uses maker-taker fees that have started around 0.07% maker and 0.20% taker, depending on volume tier. The standard swap tool uses a spread rather than the same order-book pricing.
Can Nexo liquidate collateral?
Yes. If the value of pledged collateral falls and the loan-to-value ratio reaches the platform's limits, Nexo can automatically sell collateral to reduce risk.
Does Nexo require KYC?
Yes. Identity verification is required for core services, and additional compliance or source-of-funds requests can occur for certain accounts or transactions.